What to do about health insurance when you get laid off

Block Woman stands next to a stack of copper pennies with a white square with a red cross symbol leaning against the pennies.

Did you just get laid off from your tech job? Do you fear you might? And above all, you’re wondering what you’re supposed to do about health insurance?

<insert requisite rant about how health insurance, and therefore healthcare, is unforgivably tied to employment in this country until you’re 65 or poor enough>

To be frank, the situation is often not great. But also it’s probably better than you’re imagining (i.e., catastrophizing). I hope reviewing the most influential factors in this decision will go a long way towards calming your nerves.

Important Considerations when Choosing Post-Layoff Health Insurance

What other insurance is available to you?

You probably have three or four choices available to you after a layoff:

  1. COBRA (continuing your existing insurance). COBRA lasts for 18 months. Under special circumstances, it can be extended to 36 months in CA and NY (pinko commies that they are).
  2. Your spouse’s employer plan
  3. ACA Marketplace (colloquially, Obamacare)
  4. Medicaid. Many states care only how much income you’re making right now when determining Medicaid eligibility. If your household just lost all its income, you might qualify, as weird as that might sound.

Insurance buddies tell me there are other, though much less likely, options like off-exchange health plans, including association plans, short term medical, Heath share ministries (which are not in fact health insurance). I simply have no experience with them for my clients.

What is the all-in cost of each option?

“Paying the least amount of money” is obviously one of the major goals of choosing a health insurance plan.

If you knew, in advance, exactly what kind of healthcare you were going to need in the future, you could figure out how much you’d pay overall, between premiums and co-pays and coinsurances and deductibles.

Alas, you can’t know that. Your healthcare needs can be very hard to predict. To render this a reasonable calculation, then, I usually look primarily at a plan’s premiums and out-of-pocket (OOP) max because these numbers are knowable in advance. With these (and a nod to HSA tax savings), I can see the best-case scenario (no healthcare!) and the worst-case scenario (you need a bunch of healthcare).

Be sure to take into consideration any employer direct subsidy for COBRA (as opposed to them giving you a lump sum of money with the notional label “for COBRA” on it, money which you are allowed to use for anything, including a different health insurance plan).

How close are you to fully satisfying the deductible or even your OOP max on my current plan?

A brief review of deductibles and OOP maxes:

  • After you have paid enough in healthcare bills to reach your deductible, your health insurance plan starts paying more of your healthcare bill for the remainder of the coverage year (usually this is the calendar year).
  • After you reach your OOP max, your health insurance starts paying all of your healthcare bills (outside of your premiums and prescriptions).

If you change health insurance plans mid-year, then any amount of deductible or OOP max you’ve met gets reset to $0 on the new plan. Boo. We don’t want that. You might end up paying two OOP maxes in the same year! And those OOP maxes are No Joke (especially for you ACA warriors 😬).

That means that, if you’ve already reached the deductible, and certainly the OOP max, of your workplace health insurance plan, that leans heavily in favor of choosing COBRA for the rest of the coverage year, despite its high premiums: Most or all of your healthcare needs between now and the end of the year would then be covered by insurance.

If you’re going to switch at all, switching health insurance plans at the beginning of the new coverage year (usually January 1) is usually a good move. This helps milk the most out of your deductible and OOP max each year.

To what extent would you have to change your healthcare providers?

I have a client who could have improved her finances by switching health insurance plans. At that time, she also happened to be in the midst of major breast-cancer treatment, was already pretty overwhelmed by life, and could not fathom having to find new providers. In that case, it was absolutely the right choice to make the financially sub-optimal choice (that is, to not change health insurance plans).

This is a real consideration at any time, but especially when you know you have major health things going on.

So, if you’re thinking of changing away from your current insurance, check with the specific plan whether your existing or desired healthcare providers are covered by that plan. The same insurance company can have different plans, and healthcare providers might accept one plan and not another. I’d also double check by then confirming with the healthcare providers themselves.

If they don’t, do you have the wherewithal to manage finding new providers? And even if they do, do you have the wherewithal to manage the administrative hassle of a change in insurance bureaucracies?

ACA plans aren’t great out of state: Many ACA plans provide in-network care only in-state (and cover only emergency care when outside the state). By contrast, large-employer health insurance plans generally have nationwide coverage. If you travel out of the state frequently or have kids attending school out of state and you want to cover them with your insurance, an ACA plan is likely not a great choice.

Does your spouse or partner have insurance you can get on?

Lucky you! It might not feel lucky, what with the whole layoff thing. But because health insurance is still mostly tied to employment, you’re lucky to have access to employer-provided health insurance despite having, you know, no employer.

It might seem like a no brainer to move directly onto your spouse/partner’s health insurance plan. The loss of your job would count as a Qualifying Life Event (QLE). This triggers a Special Enrollment Period (SEP), which would allow you to join your spouse’s plan outside of open enrollment.

But that “usually” brings up a good point: You have to familiarize yourself with the rules of your spouse’s plan! Information like:

  • Are you allowed to have both your COBRA coverage and the spouse’s coverage?
  • How much will adding you to the policy cost?

You have some choices (depending on what your spouse’s plan allows):

  1. Switch immediately after your layoff to your spouse’s plan (most likely allowed)
  2. Stay on your health insurance (via COBRA) until the new coverage year, and then switch to your spouse’s plan. Be sure to enroll in your spouse’s plan during open enrollment. (most likely allowed)
  3. Maintain COBRA for your own plan as long as your former employer is paying (or even if they’re not, but you really want to maintain your existing coverage for a while) and enroll in your spouse’s coverage. (less certain about this being allowed)

A note of caution about #3 above: “Coordination of benefits” between the two plans can create administrative hassles. I often see this warning phrased with general, benign language (“There can be coordination of benefits issues”). I personally interpret that as “This is going to be administrative hell because everything healthcare billing and healthcare insurance is.” I ran my interpretation by an insurance colleague, and he agreed with it, saying, “Usually both carriers deny the claim and it can take months to straighten out. Meanwhile you continue to get bills and threatening letters about not paying for the services.” Because my clients (and presumably you) already have more than you can handle of stressful administrative bullshit in this world, I’m not going to go any further with this “double coverage” consideration.

Is your former employer paying for COBRA?

If you elect COBRA, it will cost 102% of the full premium. Your employer probably covered most or even all of the premium while you were an employee. You might not have a good idea of how much your health insurance cost your employer. Spoiler: It’s a lot. And on COBRA, you will pay the full premium plus an extra 2% administrative cost.

Unless they offer to cover COBRA for some number of months. Which is great!

If you’re single, then I can’t think of a downside of your employer paying for COBRA premiums, no matter how long they will. By the end of the subsidy, you:

  • move to an ACA plan (go with God, and remember you’ll be resetting your deductible and OOP max when you change plans)
  • continue paying the COBRA premiums yourself
  • possibly qualify for Medicaid at that point, or
  • hopefully have another job and can switch to their coverage

If you are married, are eligible to be added to your spouse’s employer plan, and your employer is paying for COBRA through to the end of the calendar year (which we’ll assume is the same as the coverage year)…Great. Simple. You should be able to move from COBRA to your spouse’s employer plan on January 1. Just to be sure to sign up for their health insurance during that fall’s open enrollment!

If the COBRA subsidies last not quite to the end of the year but close, then consider sticking with COBRA the whole year and simply paying the last month or two of unsubsidized coverage yourself.

Sticking with COBRA through the entire year means you don’t change policies mid-year. As discussed above, changing policies mid-year sucks in large part because any progress you’d made towards your health insurance deductible and OOP max goes bye-bye.

Okay, those were the simpler scenarios.

Instead, let’s say that the COBRA subsidies stretch into the new year by a few months. You’re sort of tempted to get as much free insurance as possible, right?

When that employer COBRA subsidy stops, it does not count as a special enrollment period to move to your spouse’s employer plan. If your COBRA subsidy stops at the end of April, you cannot move at that point to your spouse’s employer plan.

It does count as an opportunity, however, to enroll in an ACA marketplace plan. So, with that April termination, you can either enroll in an ACA plan (and reset your deductible and OOP max…oof) or continue paying COBRA for the remaining eight months of the year. Both of which likely cost a lot.

So, if your employer subsidy stretches into the new year, ask yourself: are the benefits of sticking with your existing plan (via COBRA) worth the extra cost you’ll incur versus just switching to your spouse’s plan on January 1?

Do you have the money? You can just pay to have better health insurance.

For most people, paying for health insurance and healthcare is something they have to very carefully fit into their budget. There is no wiggle room, and often there are lots of sacrifices. But if you have enough money, you can just pay for whatever pathway is easiest for you.

Workplace health insurance coverage is, in my experience, almost always superior to ACA coverage. So, if you want to make sure to maintain good health insurance, COBRA is probably the way forward, price be damned!

Does paying for COBRA for the next 18 (or 36) months cost a lot of money? Yes. But does it make your healthcare easier to access? Most likely. And while it might be morally offensive that it comes to this in this country, I can’t think of many things worthier of your dollar than good, easy-to-access healthcare.

Case Study

I have a client who, as we speak, is figuring out what to do about health insurance for her and her family after a recent layoff. Here are the (slightly fudged) relevant bits of her story:

  • She is married, with two children, and another one on the way. Baby #3 is due March 2027.
  • The entire family is currently on her plan, not her husband’s.
  • Her husband’s open enrollment is this fall, for insurance starting January 1, 2027.
  • She got laid off by Company XYZ (yes, while pregnant…may bad juju afflict this company), and the last day of XYZ’s employee health coverage is September 30.
  • XYZ will cover 7 months of COBRA, taking the family through April 2027.

I assume they will stay on COBRA through the end of 2027. (It’s free, and that rounds out the coverage year.) Beyond that, it seems they have several reasonable options to choose from:

  1. Enroll the entire family in the husband’s plan for 2027, and transition to the new plan on January 1.
  2. Enroll the entire family in COBRA, getting it for free through April 2027 and then paying out-of-pocket for it for the remaining eight months of 2027.
  3. Enroll the husband and kids in the husband’s plan for 2027 and enroll the wife in COBRA through 2027, if not until the end of the 18 months of COBRA eligibility. COBRA eligibility is individual, so you don’t have to keep everyone together!

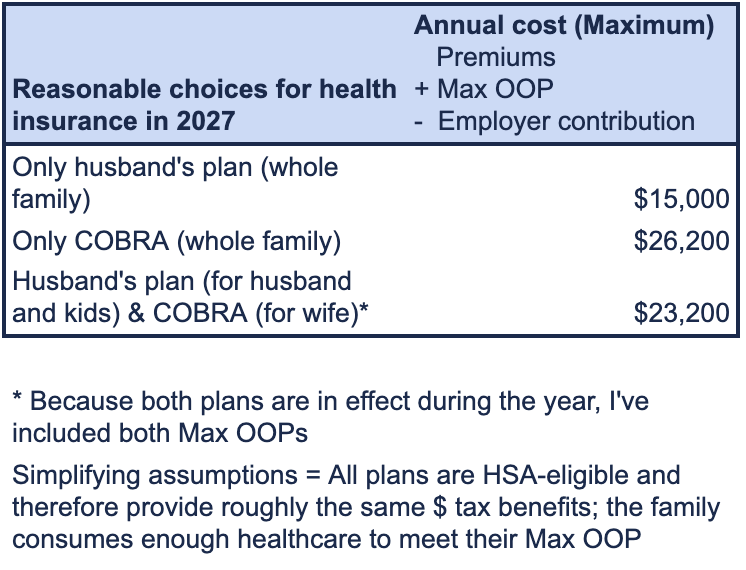
Here’s the information I need to make a reasonable, if simplified, financial analysis:
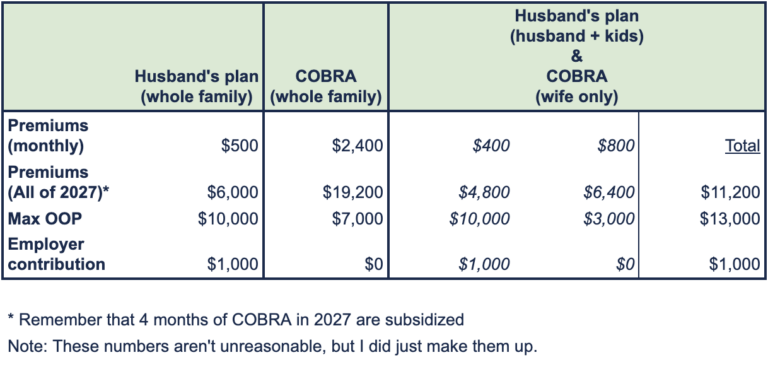
When I prioritize cost, “only husband’s plan” wins.

When I prioritize the ease of continuous care from existing providers during pregnancy and birth and infancy, some amount of COBRA (#2 and #3) wins.

When I balance cost and ease of continuous care from existing providers for the pregnant lady, “Husband’s plan (for husband and kids) & COBRA (for wife)” wins.

So, I will likely recommend to my client that:

  1. Wife stays on COBRA through 2027.
  2. Husband and existing children shift to his health insurance plan for 2027 (enroll during open enrollment this fall).
  3. When their baby is born in 2027, place him or her onto the husband’s health insurance plan.
  4. At the end of 2027, unless she has by then returned to work with a better health insurance plan, likely enroll the entire family on the husband’s plan. But we will reevaluate this during Fall 2027 open enrollment.

Resources to help you pick the right health insurance plan

I’m not a health insurance expert. (Presumably, most financial planners aren’t.) As you can see, I had to consult some just to write a blog post I could be fairly confident in! So here are some resources and experts for you to explore:

A special thanks to a couple of insurance-expert colleagues (Robert Dillard, and Mike Sheeran from Glenn Insurance) for reviewing a draft of this post and helping me understand some of the finer points of the chaos that is our health insurance industry.

Before making any health insurance decision after a layoff, I recommend doing your own research and/or working with a professional.

Reflections on 10 Years of Flow

The word FLOW is displayed in the brand colors against a dark background

TITLE: My business turns 10 today.

SUBTITLE: Holy shit, where did my 40s go.

When I launched, I was 40. Now I’m 50.

When I launched, my daughters were 2 and 6. Now they’re 12 and 16. (Math…it works!)

When I launched, we had no dog. Now we have Julia.

When I launched, I had two boobs. Now I have one. (Well, technically two. But one is an example of fine human craftsmanship.)

When I launched, my mother had two God-given hips. Now I just got home from living with her for a bit after she had one of them replaced.

When I launched, I looked for and could find only one other financial planner who focused on women in tech. Now I can barely keep count.

I still have the one, gently used husband and the one, mildly improved home.

What have I learned over the last decade?

[Note: We celebrate Flow’s birthday on May 9. If you want, read my Year 9, Year 8, Year 7, Year 6, Year 5, Year 4, Year 3, and Year 2 reflections.]

Business Lessons from 10 Years in Business

Growing your firm is much harder than maintaining your firm.

New clients are so much more time consuming than existing clients.

If you have 30 clients already, and you’re starting with one new client every month, wondering how the hell you’re ever going to serve 50 because you’re So Busy…let me reassure you that once you get to 50 and all you have to do is serve 50 existing clients (plus one or two new clients a year simply to make up for attrition), your workload will drop dramatically.

If you don’t have “perpetual growth” goals, the end of your Constant Grinding will come! (And if “perpetual growth” is your goal, then… vaya con Dios, my friend. You’re a better woman than I.)

Shifting from growing to maintaining is hard.

I started this firm with Zero. Zero clients. Zero revenue. Growing was a necessity. Grinding was a necessity.

Over the years, as I found clients and revenue, growth became less of a necessity. And at this point, I don’t need to grow at all and, for personal reasons, I don’t want to grow.

(Why do I not need to grow? Because I made a point of figuring out what my Enough is, and I reached Enough. More than Enough, really.)

That shift from “must grind!” to “just hold steady” is discombobulating. Maintenance is an entirely different mindset. It involves different processes, habits, schedules, etc. I’ve been undergoing it for about 1 ½ years now and am making progress.

Want a higher profit margin? Charge higher fees.

As I learned from JD Bruce in year 2 of owning my firm, you can focus on growth or on profit. Then experience and Michael Kitces taught me that, if you want to focus on profit, charging higher fees is the simplest, easiest, most expedient way to get there.

Hiring more people and buying new tech tools to leverage you…that might help. But tech only helps a little, and hiring people is a huge commitment.

I know that planners worry about raising their fees. They worry that they won’t get any more clients. What I have learned is that you might not get the same clients, but there are always good-fit clients at whatever price you charge.

“It’s your business, Meg. Why have you given yourself a job you hate?”

I had never run a business before Flow, so I didn’t have much intuition about how to run it. I therefore relied on external messages to guide my choices. This resulted in me doing a lot of work that I didn’t enjoy or, in some cases, outright despised.

You know that exercise where you draw a line down the middle of a piece of paper, and then on one side you write “things that give me energy” and on the other “things that drain my energy”? Over the years, I did that exercise many times (sometimes on paper, sometimes in my head, sometimes in conversation).

What gives me energy? Meeting with prospective clients, meeting with clients, creating a financial planning strategy, creating an investment strategy, and writing. (You might summarize this as “being a financial planner.”)

What drains my energy? Compliance, investment implementation, bookkeeping, hard core tax analysis, managing people, IT. (You might summarize much of this as “running a business.”)

Over the years, I’d find myself doing something I really didn’t enjoy and then chastise myself, “Meg, it’s your business. Why have you given yourself a job you hate? Not so smart, are ye?” Bit by bit I outsourced, delegated, or simply didn’t do those bits.

Do these choices sometimes mean I make less money? Probably. I’m okay with that. I’d rather have a job I thoroughly like than maximize my income (which is plenty high). And also, purely from a financial perspective, a job I like is a job I’m likely to stay in longer, which means I’ll earn more money anyways.

Financial Planner Lessons from 10 Years in Business

“So that’s why I’m so good at this.”

I’ve always been good at a lot of things. All the school subjects, all the sports I tried, etc. But I’ve never been truly excellent in any of them, in part because I’ve never been interested enough to pursue that excellence to the exclusion of other activities. I’ve often considered this a failing on my part, because it means I never stand out.

But financial planning is the ultimate liberal arts profession. It requires you to be good at a wide variety of things, know a wide variety of information, learn new things, and integrate all sorts of disparate inputs into a coherent whole. Which it turns out, I am perfectly suited to. 

My job is to be there when my clients need me.

If you consume enough industry content, it’s really easy to feel that you will never be, do, or know enough for your clients. That other planner has a better process. Oooh, this planner managed that scenario better than I probably would have. Ah damn, that new service might be useful to my clients.

Thankfully, I’ve got a pretty robust sense of self (thanks, Mom and Dad!), but even more powerful is simply observing, over time, that the thing I can do for my clients that serves them best is simply being there when they need me. This is a relationship of trust, and part of what clients are trusting us to be is reliable and present.

This is not the stuff that catchy social media posts or conference presentations are made of. But I strongly believe that it is more important than almost anything else you’ll hear about in catchy social media posts or conference presentations.

Practicing as a financial planner has made me a better conversationalist.

Remember the last time you got into “conversation” with someone who clearly didn’t care that much about what you were saying and was more or less just waiting for their chance to talk, and instead of a conversation, it was just a sequence of disconnected sentences?

Yeah. I hate that. Because I loooove a good conversation.

Practicing as a financial planner and being trained in “life planning” has made me a much better conversationalist. I ask more questions of clients (and everyone else in my life). And then ask follow-up questions to those questions. I am genuinely curious about who people are, what they do, how they feel, what their aspirations are. Conversations are instantly more enjoyable as a result.

Sales isn’t what I thought it was.

Early on in my financial planning career, I doubted that I’d ever be able to make it because I couldn’t “sell.” I couldn’t bear the thought of having the gruff handshake and the forceful personality and wearing a blue blazer and loafers and going to the country club. (Or whatever the female equivalent is.) That was my vision of what successful sales required.

Eventually I discovered that, at least for my and my firm’s needs:

Successful sales = Useful content marketing + Empathy + Trying to be helpful

I’m not trying to convince people whom I don’t have the skills to help to work with me. And for those people whom I can help, the “sale” is usually very natural. There is no need for me to ever feel “salesy.”

Metrics

Flow consists of me and the stalwart Janice, our Client Services Associate.

We have 49 client households. (I plan to stay here, maybe slightly lower. I wouldn’t want to have more than a handful more clients. Yes…I measure clients by the “handful.”)

We have juuuusst shy of $100M AUM.

Thoughts about the profession

I hope that all us planners start from an understanding that this is first and foremost a helping profession. Yes, we can make a good living at it! We can run a profitable business with saleable value!

But we’re not investment advisors. (I mean, legally we’re called Registered Investment Advisors, but functionally we do a different job.) We’re not selling software. This isn’t a very scalable business, assuming our goal is to provide human-centric, comprehensive financial planning. 

Our primary goal, as financial planners, therefore should not be profit maximization. (Again, profit is good! Yay Gordon Gecko! Capitalism rah! I just don’t believe it can be priority #1 and still provide real financial planning.)

I believe this kind of work requires a planner to have no more than 80, maaaybe100 clients. (I mean, I only serve 49 and would rather not go higher.) If you’re a financial professional of some sort directly serving meaningfully more clients, I infer from that that we simply don’t do the same job.

It is because I have such strong beliefs about what true financial planning looks like that I have become a bit grumpy about the industry (or profession) recently.

For one, all the news about VC/PE-funded mega firms that are out there hungrily gobbling up smaller shops like my own. I hope this rollup/acquisition spree goes away. I don’t know enough about those investing models to say they’re bad or good in general, but the incentives are fundamentally at odds with real financial planning. 

If you can 10x profits (or more, which is presumably what VC/PE firms target) in an established financial planning firm, then I don’t see any way that client relationships don’t suffer in the process. (10xing or even 100xing growth is just a matter of spending enough money to buy enough firms. It simply reflects the size of your wallet.)

And for two, are we financial planners or technologists? I am a financial planner who uses technology. I will likely hire someone eventually to help me make my business run more efficiently, blah blah blah. But I’m not spending my precious time exploring the depths of Claude. I’m just not. I’m spending my time learning things and improving skills that directly make me a better financial planner and that I can’t productively outsource. Maybe I’ll look back and conclude this decision was foolish, but I didn’t get into this profession to f*ck around with software; I had enough of that in my previous career. I got into this profession to help people.

Looking Forward

At the end of 2025, when all my cancer treatment was basically done, and I’d physically recovered, my psyche hit a wall. My soul was tired. So, with the help of my fellow PNW women financial planner friends, I declared 2026 to be my Year of Nope. Or, less glibly, my Year of Recuperation.

Maybe, after a sufficient period, I will feel like growing my business or my involvement in the profession again. For now, though, what I have is enough. Enough income. Enough work. Enough clients. Enough recognition. Enough giving back. Enough challenge. Enough time.

Some time in the near-ish future I will hire a consultant to help optimize my business. Someone who already knows the tech and processes and so can allow me to improve all such things without having to do the heavy lifting myself. 

In the meantime, it’s gratifying (and easy) to continually grow as a financial planner. Yes, there are webinars and articles and designations and professional forums. All of which I love. But I grow the most as a financial planner simply by being in relationship with my clients. The more experience with humans and their finances I have, the better a financial planner I become.

Personally, I want to spend time with my far-too-quickly aging daughters, my husband, the rest of my family, and dear friends. Throw in some yoga, weightlifting, and hiking, and maybe a trip here or there. I’m trying to “live my values”—using money as a tool, not a purpose—in the same way I hope I can help my clients live theirs.

Reflections on 9 Years of Flow

Block Woman stands next to a white circular cake-like object that has a single yellow flame above it.

I’ve been thinking about this blog post for over a month now.

Despite starting to think about it such a long time ago (by blogging standards), and despite generally being not at a loss for words, I found myself struggling to write about this last year in business.

[Note: We celebrate Flow’s birthday on May 9. If you want, read my Year 8, Year 7, Year 6, Year 5, Year 4, Year 3, and Year 2 reflections.]

Eventually I realized, Duh, Meg, you’ve had a physically, psychically, and emotionally exhausting 2025 so far. You just don’t have the energy to write your “usual” blog post.

Prior to last December, my business was stable, which was actually kinda…uncomfortable for me. My business coach counseled me to practice “tolerating the shit out of your success.” I was busy experimenting with this novel idea when December hit.

In December, my stage 0 breast cancer—for which I’d had two lumpectomies and radiation in 2023 and 2024—came back. I had a (single) mastectomy in early March, followed by convalescence for the rest of the month. And since then, I have been catching up.

I don’t want to belabor the whole experience, so let me share something important I took away from it:

It’s Really Nice to Let People Care for You

I often hear from people that it’s hard for them to accept help. When I was preparing for my mastectomy, my OOO, and my recovery, I made a conscious decision to embrace the shit out of letting people help me.

And it. was so. lovely. (10/10, would recommend)

My colleague, Jane Yoo, stood ready to help my clients with any urgent financial planning needs during my convalescence. (I still haven’t figured out a thank you gift that reflects the huge impact of your support, Jane. Sorry!)

My Client Service Associate Janice worked diligently to keep communication going with clients and pushing work forward in my absence.

Clients expressed concern in meetings and via email.

Local colleagues and friends brought my family meals.

Remote colleagues and friends sent us meal kits and Door Dash cards. And even the occasional t-shirt with “Thank fuck that’s over” emblazoned, conveniently, right over the breast that I had removed.

(My husband was all, “Jesus, Meg, how many people do you know?” To which I responded, It’s nice to be a woman. We support each other really well.)

Most important of all, my husband. He made the family “run” throughout it all. He made me feel loved and supported and not like a freakshow in the aftermath of the mastectomy. (Many parts of the whole experience were gross, and many more uncomfortable or painful. But the single worst experience was the first time I looked beneath the bandages just a few days after surgery. It took my breath away, but not in a good “Top Gun” sort of way.)

What Else Happened During My Ninth Year in Business?

I think Cancer and Mastectomy pretty handily trumps most other things. But other important things did happen!

We hired our own planner.

My husband and I hired our own financial planner. I had been our financial planner up until then.

Despite having enough of the technical knowledge to do the job myself, as I had been doing for years, I wanted to work with a financial planner for four reasons. I wanted:

  1. a thinking partner. Life is complicated, and getting increasingly so.
  2. a backup for me/for my family
  3. someone to put me first (as I put my clients first)
  4. someone to Identify my blind spots

Professionally, the whole process of interviewing financial planners and working with ours so far has been instructive to me, unsurprisingly.

Personally, we’ve only been working with him (yes, a man! <gasp>) since January, and I already feel the relief of knowing that someone is in my (our) corner, keeping an eye on things.

I established a formal emergency continuity plan for Flow.

One of the biggest challenges of starting an independent advisory firm is making sure your clients are taken care of if something happens to you (you die or become disabled).

I had been doing what I think most small, independent firm owners did: I arranged (informally) with a few colleagues to help serve my clients in the event I became unable to. The arrangement had meaningful inadequacies:

  1. These colleagues ran firms that probably wouldn’t allow them to assume relationships with all my clients, overnight. Which meant that many of my clients would have to be redirected elsewhere.
  2. My family wouldn’t get any monetary value out of this firm that I’ve spent nine years building.

The firm I now have a legal agreement with is big enough to accommodate all my clients, have a plan for how they’d do that, and sufficient expertise and compassion to serve my clients.

This was a very big deal for me, and I’m very glad it is finally done.

My Associate Planner left.

In mid-January, my associate planner left.

This meant I had to rejigger my plan to support clients before and during my medical OOO. ‘Twas stressful, but I got it done, and I’m quite proud of myself for how I navigated the whole thing.

Without an associate planner, I am back into alllll the weeds of financial planning. And I gotta say, it’s fun. I like the process of forming the “picture on the boxtop” from all the individual puzzle pieces of a person’s financial life. Diving back into the entire process has given me more opportunities to see what might be improved.

Leading up to my surgery, during my convalescence, and for these two or three months back in the office but “catching up,” I made the conscious decision to not think (much) about what to do about no longer having an associate planner. I simply need to “get through” (i.e., work a lot, but it is work I know how to do).

Once I am through this crush, I will raise my head again, like a curious meerkat, look at the expanse of my business and my life, and start thinking Big Thoughts again.

I continue to fall deeper in love with the Annual Renewal Meeting.

I learned from my former marriage therapist that “there is freedom in structure.”

After a client and I get past the first year’s hurly burly, the cornerstone of my client-service structure is the Annual Renewal Meeting. I love this meeting, and I love the structure I’ve created for it. My preparation is structured. My follow-up is structured. Which means I can find real “freedom” in the meeting itself; it can be largely guided by whatever feels most important for the client.

I love this meeting so much, I married it. Wait, no, I mean I wrote a whole blog post about it. 

I found my professional home.

In 2023, five women business owners and financial planners who live in the Pacific Northwest got together in an Airbnb on the beautiful, dreary coast of Washington (or Oregon, I forget…they’re very close to one another!) for a long weekend business retreat in January.

In 2024, the group met again. Alas, I was starting radiation so couldn’t attend. But in 2025, I did! (We had a bra-burning party on my behalf—bras burn alarmingly easily—as I knew by that time that I’d have to have a mastectomy.)

That weekend was profound. It felt like we’d found a real “home” in the profession. Colleagues (and friends!) who could help each other improve. Celebrate each other’s accomplishments unstintingly. Laughingly demand, “Alright, who farted!” (It was me, okay? You’re the one who fed me lentils!) And also simply hold each other (sometimes literally, sometimes metaphorically) as we talked about hard things. This industry can be full of judgment and hardness. It’s nice to have a safe, soft landing spot.

As I left our 2025 retreat, I asked, “If what I’ve already built in this business is enough to enable me to have weekends like this in my life, why am I so anxious about building anything more or different?”

Looking Forward

Since December, I have had my head down and blinders on, intent on getting myself, my family, my clients, and my business through the entire surgery “thing.” As such, I don’t have any clear ideas about what’s next… other than dedicating time to figuring out what’s next.

Even though I started writing this blog post without much direction, now that I’ve written it, I realize that a big theme is connection and relationship.

It reminds me of a favorite David Brooks opinion piece, in which he talks about the two mountains we climb in life. We climb the first when we’re younger, and on that mountain we try to achieve all the things that “society” tells us we should: money, career, awards, a home, etc. For people on the second mountain, “It’s not about self anymore; it’s about relation, it’s about the giving yourself away. Their joy is in seeing others shine.”

So, I sincerely hope that, whatever comes next, it’ll be less focused on measurement and more focused on connection.

Are you looking for a financial planner and don’t mind one who, at least once a year, does some serious navel-gazing?

How to get the most out of working with your financial planner

Pink Block Woman is on the left facing a Yellow Block on the right.

Communicate, communicate, communicate.

This is the first rule of working with a financial planner.

(It is also, by the way, the first rule of estate planning.)

If you can only remember one thing about how to have a good relationship with your financial planner, it’s a good one thing to remember.

But considering the amount of time, effort, sometimes uncomfortable introspection, and cost it takes to work with a good financial planner, it’d behoove you to figure out how to make the most out of that relationship. Yes?

Behold one financial planner’s thoughts about how you can do just that.

Ideally, the First Step Is: Hire the Right Planner at the Right Time

It’s going to be really hard to milk all the value out of the relationship with your financial planner if you hire one that you don’t jibe with very well.

I mean “jibe” in a very broad sense. You need to like their personality, their philosophy of investing and planning, and their process. If you don’t like one of those things, the relationship will likely always feel a bit like a pebble in your shoe—you can deal with it, but you’re never fully comfortable.

You have to like their “story.”

When I first changed careers into financial planning, back in 2010, I was hired into a firm with the idea that I could succeed the owner in a few years, as she was looking to sell the firm. After a few months of working at the firm, I had all sorts of anxiety about this plan.

(Spoiler alert: all those anxieties coalesced into me not buying it. Which is why I now live in Bellingham, WA, and work with women in their mid-career in tech as opposed to living in Norfolk, VA, and working with federal-government retirees.)

At that time, I had the luck of talking with a well-respected thought-leader (let’s call him Michael) in the industry about this “to buy or not to buy” choice. I mentioned that one thing giving me pause was that the retiring advisor was an “active investor.” She chose individual stocks and actively managed mutual funds, which she sold out of and bought into over time. By contrast, I have always been a passive investor: just “own the market” by way of index funds and keep costs low so that I keep as much of the market returns as possible. I don’t try to “beat the market.”

Michael told me that shifting from active to passive investing would be a hard transition to make in the firm. The clients had been told/taught/sold an active investment “story,” and I was proposing changing that to a passive story. Changing stories is really really hard.

What does this mean for you? I believe you need to make sure, before hiring a planner, that the “story” they’re telling is one that you already agree with or could see yourself agreeing with. It’s going to be bumpy if you believe one story and they’re constantly telling a different one.

I have had relationships with clients that made me feel like a bad financial planner. It didn’t seem like these clients were getting much value out of our relationship. So, by that reasonable definition, I was a bad planner. For them. (And man is that a bitter pill to swallow for someone who considers herself in fact quite a good planner.)

Upon reflection, the usual culprit was that these clients simply didn’t fully buy into the investing or planning story I was selling. It wasn’t my fault. It wasn’t my client’s fault. I mean, except to the extent that neither of us identified early enough that I just didn’t offer what they wanted or needed.

Ask Yourself These Questions

When you’re on the hunt for a financial planner, interview several. I’ve written several articles about which questions you should ask when interviewing a financial planner. There are innumerable other such articles on the interwebs.

After the interview, ask yourself these questions:

Do I trust this person? Enough, at least?

Trust will definitely grow with the relationship. But starting from a position of distrust or cynicism is, IMO, a big red flag.

Do I feel comfortable (enough) talking with this person?

Personal financial planning is pretty intimate work. It’ll be way easier and more enjoyable if you like your financial planner. You don’t have to be friends. But feeling friendly is important.

Do I agree with how this person approaches financial planning and investing?

The first step here is figuring out what the planner’s approach is.

You can ask them questions directly, when interviewing them, of course.

But before you even get face to face, consume their content. This is one reason why I write so much. I have blogged consistently for nine years. I post on social media (mostly LinkedIn) all the time. I dedicate a lot of effort to the firm’s website. I want my story, Flow’s story, to be so obvious and accessible that only the people who like that story ask to work with me.

All financial planners tell a different story. Some slightly different. Some radically different. If one planner’s story doesn’t suit you, just continue looking! There are plenty of financial planners (even if sometimes maybe you don’t know how to find them).

“At the right time” = Are you ready to do the work?

Working with a financial planner will require work from you. Some of it is merely technical, but can still be administratively burdensome (“roll your old 401(k) into your new 401(k)”). Some of it has real behavioral implications (“reduce your monthly spending by $500” or “work with this estate planning attorney to ensure your estate planning is up to date”).

This is great stuff! This work will put you in a much stronger financial position! But only if you do it. If you don’t, then you’re wasting your time and money with your planner.

I recently watched a webinar about the transtheoretical model of change. I am, of course, still mostly ignorant about it, but it seems a helpful framework for evaluating whether you’re ready to get real value out of your work with a planner. The stages of change are:

  • Precontemplation: Not ready to change
  • Contemplation: Getting ready to change
  • Preparation: Ready to change
  • Action: Making changes
  • Maintenance: Sustaining changed behavior

If you’re not ready to change, maybe don’t hire a planner yet, because they won’t be able to do much for you.

Show Up As You Would in Any Relationship You Care About

Your relationship with your financial planner is, to a large extent, just another interpersonal relationship. You probably know what makes interpersonal relationships work:

  • Show respect to the other person
  • Appreciate the other person
  • Care about the other person
  • Be responsive
  • Be honest
  • Make an effort
  • Express your needs

I owe this to my clients, as their planner. And I believe they “owe” it to me. Yes, yes, they’re paying me a fee for my work and the roles and responsibilities in the relationship are different. It’s not the same as your relationship with your husband, for example.

But, I can work with clients who pay me a fee and show up in the relationship, or I can work with clients who pay me a fee and don’t show up in the relationship. Give you one guess which type of client I’m going to gravitate towards.

Communicate communicate communicate.

Give your planner feedback. Let them know what you need that you’re not getting. It makes it so much easier for me. I appreciate this feedback!

Respond promptly when your planner asks you something. If you don’t know the answer or can’t do what they’re asking you to do, simply let them know! Just don’t leave a void of communication, which the planner (if they’re anything like me) can fill with all sorts of unsettling stories that almost always turn out to be untrue.

Some of my best relationships are with clients who have, in no uncertain terms, told me about something that was lacking in the relationship. Sometimes even about an explicit mistake I made. I apologize, fix the process, and if necessary, make the client whole. The client feels heard and respected and is also more confident in our work going forward (it seems, at least).

We run annual client-feedback surveys to try to get more of this insight out of our clients, but you needn’t wait for any official “tell us what you think” requests. Tell them what you think when you’re thinking it!

There really is no downside. If you have something critical to say, then either the planner addresses that issue in a way that satisfies you (yay). Or they don’t. In which case you’ve just found out that this maybe isn’t the right planner for you after all. Not pleasant, but still a step in the right direction.

Ask Your Planner How to Get the Most Out of Working with Them

I imagine most planners would agree with what I’ve already said. I asked some colleagues how they would advise potential clients to get the most of working with a financial planner. (Please note that I circulate in comprehensive-planning-forward, emotionally attuned professional circles, which is a small part of the overall industry. If you ask, say, a stockbroker this question, I imagine you’re going to get very different answers.)

Here’s a smattering of their answers:

Come to the quarterly meetings and ask questions. Decide on an allocation [balance of stocks, bonds, cash] and stick with it. Ignore the news. Provide data when the planners ask for it. Under the markets are efficient and if the client hears something, it is already incorporated in the markets.

For retirees: Let your advisor manage your investments. The ability for an advisor to monitor flows into and out of a portfolio is one of the most under-appreciated aspects of what advisors do for clients, particularly when considering risks associated with cognitive decline and elder abuse.

The ability to put aside their ego and what they think they know, to explore with curiosity what they don’t know.

Bring your life partner, especially if you generally avoid talking about $ together.

I feel like the clients who I see make the most progress are the ones who are most engaged. They come to meetings to listen with few distractions, ask questions, and reach out proactively for guidance around decisions … instead of informing me after.

Show up, ask questions, listen, ask before acting.

The clients I work best with are the ones that come to the meeting with questions or ask questions as we’re discussing things in the meeting. They also come with updates; when asking questions about selling rental properties, they have the rent and other P&L numbers. When they have questions about investments, they have a rough idea of how much cash leftover they have each month/year.

What I think is valuable in the relationship isn’t necessarily what you think is valuable. I’ve certainly had clients for whom I thought I wasn’t providing much value who have then expressed profuse thanks for my work. Some clients who exclaim, “Please don’t fire me!” after not communicating with me for many months.

So, perhaps I’ll end with a final piece of advice:

Figure out for yourself what would make your work with your financial planner feel most valuable to you. And then communicate, communicate, communicate that to your planner.

What could you do to get more out of your relationship with your financial planner?

Protect Your Parents from Scammers.

A blurred Block Woman is next to a tall yellow block with side tufts of hair and a shorter blue block with white hair.

A couple weeks ago, I almost-not-really got scammed.

A man called me from Capital One’s fraud department to confirm that I had not, in fact, made some purchases. (No, I didn’t buy anything from Turkish Air…but that does sound kinda fun, now that you mention it.)

My guard went up pretty quickly because I’m aware (because of both my age and my profession) that scammers try to get personal information from you on the phone in this way. But it was only mildly up, so I spoke with the man for a few minutes, getting increasingly anxious. He pushed on, quashing any minor protestations of suspicion. When he finally asked me to go get my credit card so I could give him a piece of information from it, I knew it was a scam and said I’d be hanging up now. He abruptly did the honors himself.

It rattled me. Why did I spend any time on the phone with this man? I know the rules: Financial institutions (banks, credit card companies, brokerage houses, Social Security, the IRS, and on and on) will never call you and ask for information. And yet I, a cognitively healthy, informed person had not just immediately hung up. I had spent several minutes actively trying to figure out if it was a scam or not. The longer I’m on the phone, the more vulnerable I am.

If I didn’t recognize it immediately as a scam, what did this mean for my older loved ones? I mean, my parents and my aunt are all in their 80s and really healthy…but they’re still in their 80s and stuff just slows down. (Hey, Mom and Dad…wassup. Erm…you’re still great, even with your 80-year-old brains.)

This started me thinking about “What advice can I give them that is extremely easy and simple to execute that won’t require any judgement in the moment?”

I settled on advising them to say this every time a financial institution calls: “Where are you calling from? Thank you. I’m going to hang up and call back.”

Then go find the institution’s phone number (from a statement, the back of the credit card, or by typing in the URL of the website itself and finding it on the website; you can’t just search for the website because scammers can manipulate search results) and call the institution yourself. I also told my loved ones, “And you can always call me if you have any questions about what’s going on or what you should do.”

I shared these thoughts on LinkedIn, and it clearly hit a nerve. Many people reposted it. Many people shared their concerns about their own loved ones being scammed.

But what got me is that many people also shared other advice for how to deal with this situation differently or how to deal with other situations (An email! Malware on your computer! Someone at the front door!). A friend also observed that her mother would never use the script I suggested because she’d consider it rude and the mother was raised to avoid being rude at all costs.

So, while clearly people liked my specific advice, it also clearly wasn’t sufficient. But I remain committed to the idea that, whatever the solution is, it has to be simple, easy, one-size-fits-almost-all-situations, and reflexive. We can’t expect anyone to be making judgments in the moment about whether it’s a scam or not.

Why This Is So Important

You want your parents to have health insurance so that medical needs don’t bankrupt them, right? You want them to have car insurance so that if they get in an accident, they don’t need to pay out of pocket to replace an entire car or in case someone sues them for $100,000, right?

These are examples of potential economic devastation wrought by a couple different risks.

Getting scammed is a risk that can be just as disruptive and economically devastating. A big problem, it seems, is that we have no way to “offload” that risk onto anything like an insurance company. (If there is such insurance, lemme know!) So, we are left only with making sure it never happens in the first place.

From $5,000 in digital gift cards that your parents might be persuaded to buy and then give to a scammer, to unknowingly giving access to their entire bank account, and possibly their investment accounts. (Anyone else see The Beekeeper? That’s what I’m talkin ‘bout. Alas, I am not remotely as effective as Jason Statham.)

We have to take this seriously.

Stay Abreast of the Scam “Landscape”

The book Mom and Dad, We Need to Talk: How to Have Essential Conversations with Your Parents about Their Finances provides a lot of resources to help you and your parents stay up to date on current scams and how to protect yourselves:

I was going to also include the Consumer Financial Protection Bureau here, because the book mentions it, and it is reputed to be successful in helping people recover money if they’re scammed. I just don’t know what shape it will have (if any) once Elon Musk/DOGE/President Trump are done with it. Which is just so uncaring and horrible for our vulnerable loved ones.

The book has an entire chapter dedicated to “Talking to Your Parents About Scammers,” that would be a very practical how-to resource for you.

Make a Plan with Your Loved Ones

My first draft of this blog post had all sorts of specific advice about how to help your parents and other vulnerable loved ones protect themselves against scams. But there’s just so much (too much) advice out there! The blog post got longer and longer, and the longer it got, the less useful it got.

Ultimately, the best advice will really depend on the type of scam and the type of person. You know your loved ones—their finances, their personality, and their habits—better than I.

So, my advice to you is:

Take this seriously. Talk with your loved ones about it and about why it’s important to create a plan to protect themselves. Work with them to create a plan that will work for them.

  • Is it a specific script they can always say on the phone?
  • Is it a rule that they always call you before responding to any communication about finances?
  • Is it requiring your confirmation for them to move any money over, say, $500 out of their accounts?
  • Is it a rule that they never ever click any links in an email? (I could definitely benefit from following this advice, too. It’s just so ingrained!)
  • Is it a rule that if something “weird” happens on their computer (which we know could be malware), they call you before doing anything with it?
  • Is it turning over management of certain accounts to you, so they can’t move money out of it?

And then, much as you (should) revisit your financial plan regularly (say, once a year), you should revisit this issue with your loved ones regularly. People forget. Scams evolve. The world changes.

I’m not an expert on this matter. But I am enough aware of human behavior to know that whatever the plan is, it has to be simple, easy to follow, and not require judgment in the moment. It needs to be muscle memory, basically.

Even if you’re not a big-time caregiver (yet?) for your loved ones (you’re not accompanying them to medical appointments or coordinating in-home nursing care, for example), this is a kind of caregiving that you can—and should—start early. An ounce of prevention and all that.

Do you worry about vulnerable loved ones? Do you want to work with a financial planner who can help you consider your total financial picture (which is usually way bigger than you think)?

Unsexy Finances for People Solving Important Problems

A dark gray Block Woman stands in front of a black background wearing a light gray head scarf.

I’m thinking of changing my firm’s tagline to “Unsexy finances for people solving important problems.”

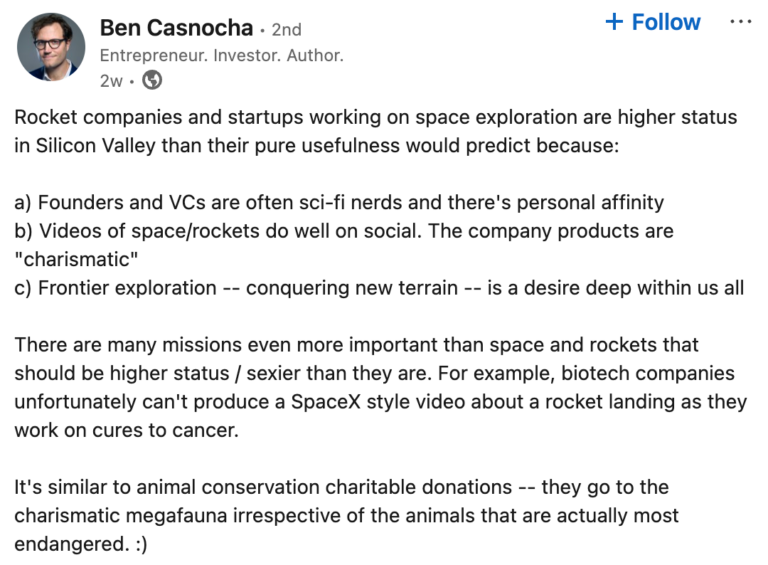
A friend of mine pointed me to this LinkedIn post:

And it got me a’thinkin’.

(FWIW, I don’t know this Ben chap from Adam. His post simply struck me.)

In tech, yes, there’s a tendency towards optimization, towards complexity, towards sexiness.

The “sexy” problems, the “sexy” solutions: they get all the media, all the headlines, all the clicks, just as Ben Casnocha mentions above.

But the important problems? Not so much. Why? Well, that’s above my paygrade. But if we truly valued “important” over “sexy” in this society, teachers would get paid a heck of a lot more.

The same thing goes for personal finance.

Everyone is attracted to sexy (complicated, optimized, conversation-worthy) answers to financial questions. But you know what I think? Sexy finances are a distraction.

I think your finances should enable you to focus wholeheartedly on your life, not distract from it.

Yes, there are some aspects of personal finance that are unavoidably complicated. The Internal Revenue Code makes sure of that. But much of the complexity is of our own making, and we can undo it or avoid it with our own hands.

Wouldn’t you like to understand your finances, know that your finances are taken care of, and then put them out of your mind because you’ve got more important problems to solve?

I want to help those people who are solving important problems rather than seeking meaning in their finances. And I think unsexy finances are the way to do it. Personal finance can be challenging. It can be (it is!) important. But it shouldn’t be sexy.

There are a lot of important problems that need solving out there. Important problems in the workplace, like the biotech problems mentioned in the LinkedIn post. (Hell, I’ve got a client right now working on cancer cures, as the LinkedIn post mentions, and it’s simply awesome to witness.)

Also, problems like:
“How do I raise my children while also pursuing a career I care about?”
“How do I protect people in my community or country?”
“How do I carve out time to create art while living in a really expensive place?”
“How do I care for my aging parents who live in a different state?”

I can’t solve almost any of them, but I can help support the people who are. I want to help you tell the difference between “unavoidably complex” and “nope, we can just keep this simple.” I want to help you get through the unavoidably complex things as easily as possible.

No matter if you work with me, another planner, or rock it DIY-style, my advice is the same: keep your finances unsexy, and reserve all that sexy-time energy for the important problems in your life.

What important problem are you solving?

What Clients Really Care About (from our 2023 and 2024 Client Feedback Surveys). Do You Agree?

Two Block People on either side of a piece of wood for a table with a multi-colored puff ball above them.

After two years of annual client-feedback surveys, I have learned two important things:

  1. I suck at writing client-feedback surveys.
  2. Talking with a financial planner who really knows and cares for you is extremely valuable. Maybe the most valuable.

As for #1, let’s say only that I am thankful for clients who, as it turns out, run customer-feedback surveys for giant tech companies and are experts in the matter, and furthermore are willing to share their thoughts after year one’s sub-optimal effort.

Moving on…

As you read below about what clients get out of meeting and talking with us, I’d love for you to take a moment to imagine what it could be like for you to have someone (a financial planner) in your life whom you could meet with and talk with in this way. Would you love it as much as our clients do? If so, what is holding you back from working with a planner?

The not-well-made-but-still-useful 2023 survey and the 2024 survey gave us many insights, but the biggest one across both surveys was: Clients value meeting with us. A lot. (Most clients, most of the time.)

From 2023’s survey, we learned that clients want meetings more proactively scheduled between their Annual Renewal Meetings. We had been proactive about scheduling that one, lynchpin meeting every year. But we often then left it up to them to reach out when they wanted to meet mid-year. (Turns out, wanting to meet and getting around to scheduling a meeting are two very different things. As a result, some clients weren’t meeting with us as often as they wanted.)

So, in 2024, we made a simple but surprisingly powerful change: In our annual meeting, we scheduled not only next year’s annual meeting but also a mid-year meeting with the client.

Usually, that mid-year meeting is six months out. If there is something specific going on in a client’s life that needs sooner or more frequent conversations, we schedule meetings accordingly. Clients now always have at least one meeting with us on the calendar, which you know is reassuring! (Well, almost always, because I can’t guarantee anything.)

From 2024’s survey, we learned that, out of many different things we do for clients (tax return review, open enrollment advice, email reminders, etc.), clients value the meetings, or perhaps more accurately, the conversations with us the most.

Why do clients get out of these meetings? The meetings can (paraphrased from the survey responses):

  • Remind clients of The Big Picture
  • Provide accountability
  • Answer tough questions
  • Give peace of mind
  • Provide reassurance that someone is looking at all this finance stuff and that the plans are on track (or that we’ll tell you if they’re not!)
  • Help you navigate big life events (like having your first child)

What Does This Mean for How We Serve Clients?

Happily, I don’t think we need to change much in order to honor the feedback we got from clients. We’ve worked hard over the last several years to find a cadence of meetings and a focus for our meetings each year that serves both our clients and us well. (As it turns out, serving one well is often synonymous with serving the other well.)

The cadence of:

One Big, Comprehensive Annual Renewal Meeting
+
One Mid-Year Check-In Meeting

is good for most of our clients most of the time.

Some clients, some years, need more meetings. Either their lives or their finances are going through something challenging or complex (Having a baby! Moving! Going through an IPO! Buying a home!), and we simply need to talk more frequently. Cool. That’s the nature of the work. It waxes and wanes.

You’d like to think that “finances! So objective! So number! I can certainly just create a well-defined process and calendar around this, press Start, and off we go, in perpetuity.”

And yet. And yet.

One of my favorite ideas is that my job as a financial planner is “to be there when you need us.” Hell, it’s even on our website!

The challenge? “When you need us” is pretty unpredictable. So how do we run our business so that we can reliably “be there for you when you need us”?

I need two things to be able to honor this value:

  1. the time to meet with you
  2. enough of the the right energy to meet with you

To get both of those things, I think the solution is:

  • Have few enough clients. Fewer clients = lower level of recurring work = I have space in my calendar and a sense of “spaciousness” for those higher-need situations.
  • Having a personal practice like meditation. This helps me show up for you in a way that is grounded, receptive, and curious.

We already do those two things (though I benefit from continually reminding myself of their importance). So I won’t be making any dramatic changes based on these survey results.

Sure, there are some tweaks to further refine how we work with clients. I can’t imagine that will ever go away. But we seem to have gotten the most important stuff right, and I want to continue to enable me and the rest of the team at Flow to continue to do that.

Other Things Clients Value

Lest you think that the only thing clients get out of this work are our sparkling conversational skills, clients also called out that they value:

  • Us following up with them to make sure their tasks get done
  • Quick responses
  • Attention to detail
  • Knowing that they can reach out to us any time about pretty much whatever
  • The personal updates in our quarterly client newsletter (Everyone always wants to know about Janice’s cows, Yerim’s and my dogs, the family trips, and sometimes the not-so-pleasant updates, like scary health diagnoses!)

I’ve only done feedback surveys for two years now, so there’s a lot we haven’t asked clients about. But it was interesting (and helpful and reassuring) to see this trend already just two years in.

I’m looking forward to exploring more aspects of our client relationships and service and value in future years and see what else we can unearth from our clients. The goal is always to identify what our clients want and need, not what I think they want and need, to be happier with both their relationship with us and with their lives and finances.

Would you find it valuable to work with someone who deeply knows you and your finances and who is committed to being there for you when you need her? Reach out and schedule a free consultation or send us an email.

Sign up for Flow’s twice-monthly blog email to stay on top of our blog posts and videos.

Top 11 Reasons that People Reach Out to Us for Financial Planning Help

1 pink and 1 blue block women sitting across a white table from each other

Do you recognize yourself in any of these situations?

While everyone’s finances are complicated (if nothing else, because their lives are complicated), there’s actually a fairly short list of reasons that people reach out to us, to work together.

I hereby present to you the most common reasons that people want to work with us. In no particular order:

  1. I have a giant pile of company stock. I know I’m supposed to do…something. But I’m paralyzed.
  2. Um, my company just filed to go public. I haven’t done anything to prepare. Halp!
  3. My company is probably going to go public soon. I have a ton of options (RSUs, stock) in my company, and I want to do the right thing.
  4. I just went through an IPO. Now I have a lot of company stock, and more coming, and OMG what am I supposed to do? I don’t want to get killed on taxes.
  5. I make way more money and have way more money than anyone in my family ever has, and I have no idea how to handle it.
  6. Finances have gotten too complicated. I don’t know how to confidently manage them any more. I’m afraid I’m doing something wrong.
  7. I have all this cash. Like, a lot. Too much.
  8. We had a giant tax bill last year, and I don’t want to go through that again.
  9. I need to leave my job. I need to not work for a while. I am burned out. But that’s scary and I have no idea how to do it. What about health insurance?
  10. I’m getting married, and we need help joining our finances and learning how to manage them together.
  11. I want to retire early.

(An aside: Before writing this list, I thought about it for a while. Then I wrote down all these reasons, thought and wrote some more, then counted them, and ta da! An exact 10! It’s as if the gods wanted me to have a clickbait-worthy title for this blog post. Then I thought of an 11th. Dammit.)

Our work together ends up addressing waaaaay more than these reasons, of course. Financial planning is, or at least should be, a remarkably comprehensive endeavor. Just look at how we run our Annual Renewal Meeting if you want some flavor. It’s just that no one has ever scheduled our short intro call because they wanted to talk about, oh, their estate planning documents or disability insurance coverage. (Which are super important! Make sure you have that stuff done!)

Are you dealing with one of these situations yourself? Reach out and schedule a free consultation or send us an email.

Sign up for Flow’s twice-monthly blog email to stay on top of our blog posts and videos.

Disclaimer: This article is provided for educational, general information, and illustration purposes only. Nothing contained in the material constitutes tax advice, a recommendation for purchase or sale of any security, or investment advisory services. We encourage you to consult a financial planner, accountant, and/or legal counsel for advice specific to your situation. Reproduction of this material is prohibited without written permission from Flow Financial Planning, LLC, and all rights are reserved. Read the full Disclaimer.

What It’s Like to Work with Flow: The Annual Renewal Meeting

Two Block figures face each other across a tabletop that has 3 pieces of white paper on it.

Most people have no idea what working with a financial planner is like.

Every prospective client I speak with has questions about what it’s like to work with us at Flow. While nothing can replace the actual experience, I hereby swear to write as much as necessary to paint that picture! No word left unturned!

Let’s start with our Annual Renewal Meeting.

Why? Because it is the keystone of our ongoing relationship with you, year after year.

Did you notice that we call it a Renewal Meeting, not a Review Meeting? That’s on purpose! Yes, we review the last year so we can celebrate your accomplishments and progress. More importantly, we renew your vision, your energy, and the plan to bring that vision to life. I think that’s exciting!

How You Can Use This Post

While I’m writing this primarily for those of you who might want to work with us at Flow, I can see it being potentially useful for several groups of people:

You are looking for a financial planner. You can judge whether Flow might be a good fit for you, and you can use our description to help evaluate other planners and their services.

You are already working with a financial planner. You can see if we’re providing something for our clients that you’re not getting from your planner (and would really like to get). Or maybe it’ll simply reassure you that your planner is great or “thank goodness they’re not like those Flow weirdos.”

A Disclaimer (Naturally): Things Always Evolve

After over eight years in business, I have tried a lot of different ways of doing things. Many things. Many ways. So, it’d be foolish to imply that the way I approach the Annual Renewal Meeting now is definitely the one I’ll still be using in five years. But I also have experimented enough to know that the current way is good and sustainable and I’m in no rush to change it.

(I wrote an article for an industry blog explaining why I moved to the Annual Renewal Meeting from my previous approach.)

Why You Should Care about the Annual Renewal Meeting

If I had to choose a single reason that the Annual Renewal Meeting is important to you, I’d say: It forces you (and your partner) to set aside meaningful time to sit with, think about, and talk about your life and finances.

Left to our own devices, most of us won’t do that. Sure, we’ll low-key worry about our finances all the time, but we won’t have an actually helpful, organized conversation about it. Why would I do that nonsense? Amorphous anxiety makes me feel alive, alive I say!

Isn’t that a ringing endorsement of working with a financial planner? “Work with me! I’ll…schedule time on your calendar!”

But of course, you know how important that actually is sometimes. Having sat with enough clients in this way for years now, I find it kinda beautiful to observe what often comes out of this time and focus, especially with a third party (i.e., me, in case that wasn’t obvious) who really cares about you being happy and fulfilled.

But wait! There’s more!

You are more confident and comfortable, because now you know what’s actually going on across your entire financial life. How has your net worth changed, and why? How are your investments performing? Are you on track to max out your 401(k) by year’s end? How much cash do you have?

You now know what you need to change, instead of just stressing over what might need to change. Your life and finances change over the course of a year. Someone needs to figure out how you need to change your finances in response. That’s us. We’re the someone.

You know which top one or two priorities to focus on. You’d be overwhelmed if we just gave you an undifferentiated list of all the stuff you need to think about and do to improve your finances.

You can get excited about what comes next! Most of us get trapped into thinking about only the demands (and joys!) of the now. We neglect to look ahead to what we can build our lives into. The Annual Renewal Meeting is your chance to do that, along with someone who’s an expert not just in personal finance, but in your personal finance. (Again, me. That expert is me.)

Behind the Scenes: How We Prepare for the Meeting

Of all the hours spent on the Annual Renewal Meeting, the vast majority of them are spent behind the scenes, us beavering away, invisible to you. You’ll see the results of that work in the meeting, and I thought it might be helpful to see how we do that work.

#1 Understand the Big Picture

We want to start with a strong handle on the Big Picture of your financial life, kind of like looking at the picture on the boxtop of a jigsaw puzzle. When we start at that Big Picture level, we better understand how the details fit in, and we can more usefully discuss any issues you bring up.

To build that picture for ourselves, we look at:

  • Your Written Plan (your statement of financial purpose, goals, and net worth)
  • Your answers to our pre-meeting questionnaire
  • Notes from last year’s Annual Renewal Meeting and meetings since then
  • Recent email conversations
  • Our “Future Meetings” document (a “dumping ground” Google doc where we record thoughts throughout the year as we think of something that might be important for you)
  • Tasks previously assigned to you or us

In all this prep, we use a “past/present/future” framework to try to create a unified picture of your life. We want to understand what has come before (and what we can learn from it), what’s happening now (that’s the only stuff we can change), and what might happen in the future (that we should start thinking about and maybe planning for).

We’re regularly building a list in the backs of our heads of: What are your strengths? What are the opportunities for you to improve? What are the most urgent and/or important things for you to focus on?

#2 Review the Financial Planning Technical Stuff

We review a long list of technical things in your financial life. This part is probably more along the lines of what you’d expect of a meeting with a financial planner. Maybe you’re interested in the specifics, or maybe you glance over the list and think, “That’s cool. Looks like you know what you’re doing. Carry on!”

Would you benefit from reviewing these parts of your financial life, as we do for the Annual Renewal Meeting? 

  • Education funding: Investments, savings rate, account balances for your kids’ education
  • Cash flow/Savings rate: For financial independence (retirement), shorter term goals
  • Paystub review: 401(k) and HSA contribution status, anything … peculiar on your paystub
  • IRA Contributions: Eligibility for IRA contributions (direct Roth, backdoor Roth) and a plan for when to contribute and how to fund the contribution
  • Cash cushion: Cash you have vs. cash you need, a plan for the “too little” or “too much,” interest rate
  • Company stock: Concentration in your total portfolio, sales strategy, upcoming expiration dates, options-exercise strategy
  • Your child’s age: If they’re turning 16, auto insurance and liability insurance; if they’re turning 18, preparation for them becoming legally independent (like HIPAA release)
  • Your age: Changes to your contribution limits for your 401(k), IRA, or HSA; eligibility for withdrawing penalty-free from retirement accounts
  • Withdrawal rate/dollars: If you’re living on your investment portfolio, both historical and projected
  • Coast FIRE analysis: If we suspect you might be close to or in Coast FIRE (Don’t know what that is? More or less no one does. Read the linked blog post. It’s a powerful concept!)
  • Estate planning: Documents (like a will and power of attorney), beneficiary designations (reviewed every other year)
  • Insurance: Life, long-term disability, homeowners or renters, umbrella liability, auto, etc. (reviewed every other year)
  • Taxes: Check in on your relationship with your CPA, revisit any parts of our tax-return review that warrant it, and several more tax-related topics:
  • Tax strategies for an unusually high or low-income year: IPO years (high income/tax rate!) or sabbatical/layoff years (low income/low tax rate!) give us fleeting opportunities: charitable donations, Roth conversions, selling investments at a gain, etc.
  • Charitable giving: How much you are giving vs. how much you want to give, how you’re donating the money (credit card, stock, directly to charity vs. Donor Advised Fund, etc.)
  • Net Worth: Change from last year, explanation for change, and whether that change is acceptable or you need to change something
  • Account consolidation: Opportunities to simplify your financial life by reducing the number of accounts you have—either bank accounts or investment accounts

#3 Review Investments

Accounts We Invest for You

We can do the most for the investments we manage for you. We look at:

  • Your Investment Policy Statement (a document that states what we’re investing for and the high-level strategy for investing). Does it need to change due to changes in your life?
  • Your actual investment portfolio. How closely is your portfolio abiding by the strategy in the IPS? Has it veered away from it? What changes do we need to make to bring your portfolio back to target?
  • How much cash is in your portfolio (more of an issue for clients living on their portfolios). Do we need to generate more?
  • Special investments you own, like company stock or other concentrated stock positions. How concentrated are you?

We send this review to you several days before the meeting, with a video explaining our review and any changes we recommend.

Why do we do this part ahead of time? Because usually you just want to know that we’re paying attention to it and to know generally what’s going on in your portfolio. Beyond that, we’ve usually found that clients don’t have many questions. So, I’d rather use the meeting time for you to talk, instead of me droning on about your investments.

Accounts We Don’t Invest for You

We don’t (usually because we can’t) manage certain accounts for you, for example, 401(k)s, HSAs, education 529 accounts, and company stock plans. We do, however, still make sure they’re invested appropriately for you:

  • Are your investments low-cost enough?
  • Is the account invested with an appropriate balance of stocks and bonds (i.e., your “asset allocation”)? Do you need instructions for how to “rebalance” it?

If it’s an HSA, we look to see if you have been withdrawing money from it to pay medical bills. Yes, I know that’s the whole purpose of this account, but usually clients are better off using it as a retirement account that they don’t touch for many years.

And sometimes clients have “play” accounts: accounts that they invest on their own, usually in individual stocks, crypto, or other “gambles.” The only thing we monitor here is the size of the account. Has it grown to be too large a part of your total investment portfolio?

#4 My “Woo” Preparation

All the prep I just described is essential. There is no Annual Renewal Meeting without it. And by itself, it’s enough! You can have a good, even great, meeting with it.

I have found two practices that make me even better at running an Annual Renewal Meeting:

#1 Five to ten minutes of savanasa-like rest after reviewing all these details. Savasana (translated as “corpse pose”) is the final pose of any physical yoga practice. It looks a lot like just lying there, eyes closed. ‘Cause it is. It is an opportunity for your body to integrate all the benefits of the physical practice you just finished.

As a financial planner, I take a similar short period of quiet and reflection (I might even close my eyes!) after all the heavy Brain Work. And this savasana helps me just sit with all that information, integrating it at some unconscious level. I have found that I emerge from the savasana with a better understanding of what is truly the most important thing for you.

#2 Five-minute meditation right before the meeting. This tames the Monkey Mind a bit. With a calmer mind, I can simply be more present with you. I am more likely to truly “hear” you.

Told you…kinda woo.

The Actual Client Experience: What Happens in The Meeting

So far, I’ve told you nothing about your experience in this Annual Renewal Meeting. It’s been all “me me me.”

What do you experience, as a client? Behold:

Before the Meeting

We ask you to give us some information:

  1. Fill out a questionnaire
    You can see our questionnaire here. (We have a slightly different questionnaire for our clients who are living off their investments.)
  2. Provide a recent paystub
  3. Make sure that all your financial accounts are up to date in our financial planning software

We can still have a useful meeting even if you provide us with nothing (I know because this has happened not a few times). It’s just more useful when we get more input from you.

You should also receive an email with a short video review of your investments (as described above) in the week prior to the meeting.

During the Meeting

Here’s what we talk about in the meeting itself:

Check-in

Yeah, yeah, there are always the basic conversational pleasantries that make the world go round. I genuinely enjoy seeing dogs and cats and babies and seeing what you’re eating for lunch and hearing about your latest vacation or even the latest chaos at work.

This usually leads pretty quickly and naturally into you talking about what’s on your mind and heart, which will end up being the focus of the meeting.

strengths, opportunities, and priorities

We like to lay out early in the meeting our high-level assessment of your finances: 

  • Strengths: from a good savings rate to a lot of flexibility in your investment portfolio to demonstrated grit in your career or personal life
  • Opportunities for improvement: Could your cash cushion be usefully higher? Do you still need to get your estate planning documents drafted?
  • Priorities: Of all the parts of your financial life, what are the few that we think best deserve your time today and your work in the near future?
Review the last year

We review your answers to these three questions, which we asked in the client questionnaire:

  1. Tell us about one thing you’ve done in the last year that you’re proud of.
  2. Tell us about one thing you’ve spent money on in the last year that brought you joy.
  3. Tell us about one organization or person you gave money or other resources to that made you happy!

This discussion helps reinforce how to use money to bring joy and meaning to your life. Sounds pretty helpful for making financial decisions moving forward, eh?

This personally is one of my favorite parts of the meeting: it’s a celebration.

Review net worth

Net worth is one of the few metrics we track every year. We want to know how it’s changing and why. Did the stock market help or hurt? Did you save a lot? Spend a lot?

Over time, we generally like to see it go up. But not always! Depends on your plan.

Review goals

We review your goals (which we record in your Written Plan):

  • Have you accomplished a goal? (always fun to check those off)
  • What progress have you made towards existing goals?
  • Do you have new goals?
  • Have the priorities of your goals changed?
  • Are some goals not really important to you anymore?

This is not a complex process. It is, however, incredibly valuable. This part of the meeting, using the Written Plan as guide, provides a simple structure to make sure we’re still making financial decisions “in the right direction.”

What you want to talk about

Although I’m dedicating only a few sentences to it here, this is perhaps the most robust part of the. meeting. Depending on what you want to talk about, we can go deep technically and emotionally. We want you leaving the meeting with a deeper understanding of what you need to do and why.

What we want to talk about

This is the stuff that we prepared ahead of time.

Wrap up

We’ve just spent two hours talking about a lot of things; you’re not going to take all that with you. This wrap-up helps cement in both our minds the parts that you will carry with you.

We do three things:

  1. Schedule the next meeting. (It’s comforting to everyone to know this is on the calendar!)
  2. Agree to the work we each have to do after the meeting.
  3. “What are you taking away from our conversation today?” Your reflection here is another favorite part of the meeting for me. It’s such a satisfying window into your brain and heart.

After the Meeting

We send you an email, listing the tasks that we agreed to in the meeting, and provide full notes from the meeting.

I hope seeing “behind the curtains” of our Annual Renewal Meeting (the what, why, and how) gives you a better appreciation for the practicalities of working with us. Armed with such information, may your search for a financial planner be more informed and more confident!

Would you like the comfort and confidence that comes with such a thorough annual focus on your life and finances? Reach out and schedule a free consultation or send us an email.

Sign up for Flow’s twice-monthly blog email to stay on top of our blog posts and videos.

Disclaimer: This article is provided for educational, general information, and illustration purposes only. Nothing contained in the material constitutes tax advice, a recommendation for purchase or sale of any security, or investment advisory services. We encourage you to consult a financial planner, accountant, and/or legal counsel for advice specific to your situation. Reproduction of this material is prohibited without written permission from Flow Financial Planning, LLC, and all rights are reserved. Read the full Disclaimer.

Meg’s Musings: On Being a Financial Planner

Block Women is to the left of the image with a black background cutout overlayed a brown wood wall.

Back from several days in San Francisco—celebrating my wedding anniversary, admiring a friend’s potato-shaped dog, meeting with a handful of clients, enjoying the hell out of San Francisco, and generally “checking out” from the daily grind—it’s prime time for another edition of Meg’s Musings.

Technical, Behavioral…and Bureaucratic

In my profession, “real” financial planners know that in order to serve our clients well, we need two kinds of knowledge:

Technical. This is what almost all our education and training is targeted at. How does the tax code work? How much insurance of what kind do you need? Etc. Those letters after my name (CFP®, RICP®)? Those are almost entirely indicative of technical knowledge. You want facts? I got yer facts. Right here.

Behavioral. This is a more recent entrant into the canon of Good Financial Planning, but it’s a growing focus, and at least my entire professional community is on board. This is the work of acknowledging clients’ emotions, and using emotions and behavior to improve their lives and finances. (I also, as it turns out, have letters for this domain of knowledge! I just don’t usually use them. But if you like, you can imagine RLP® after my name. That stands for Registered Life Planner®.)

The longer I practice, and more time the federal government, state governments, and corporations have to “improve” things, the more I believe a third knowledge category deserves acknowledgment:

Bureaucratic. This is the category of knowledge that we must bring to bear when we actually want to implement all the strategic and tactical decisions my clients and I make. And I think it gets more obvious and important every year.

A fantastic example is the knowledge required to roll over an old 401(k). Most clients understand the technical and behavioral merits of doing this. But Oh. My. God. Have you tried to roll a 401(k) to another account at all recently? If you have, maybe you already know what I’m about to say. If you haven’t, just ask your friendly local financial planner.

From inefficient processes (“Really? You have to mail me a check? And then I have to turn around and mail that self-same check to the new 401(k) company?”) to outright mistakes (“What do you mean you deposited my old Roth 401(k) money into my new pre-tax 401(k)?”), it can be a nightmare. I have an entire blog post dedicated to avoiding common 401(k) rollover mistakes.

After years of observing and helping clients roll old 401(k)s into new 401(k)s or IRAs, we’ve accumulated quite a list of tips and tricks to help it happen, perhaps not quickly, but successfully and without giant mistakes.

That is, in my opinion, a tremendous value we financial planners can offer to clients, who might otherwise:

  • Not do it at all. Like the client who left their old 401(k) alone for over 10 years, resulting in the money getting sent to the state’s unclaimed property division, whence it is proving extremely difficult to extract it, or
  • Do it and something ends up wrong. Like the client whose after-tax/Roth money was deposited in the new 401(k)’s pre-tax account. Don’t worry, we resolved that. or
  • Do it, push through all the hurdles, actually do it correctly, but be uncertain and stressed out along the way.

Prior to “retiring” (to be a stay-at-home dad) back in 2016, my husband had worked for several years (as a software programmer) at a company that produced security software. He used to characterize his job—at first jokingly, and increasingly cynically over time—as writing code to undo the effects of the shitty code that other people had already written. Yes…there’s obvious value in undoing badness, but damn, wouldn’t it just be better if the shitty code never existed?

In that same spirit, this Bureaucratic Knowledge is one of those incredibly useful things we financial planners provide…that I really wish we didn’t have to. It’s just getting us back to Net Zero. It’s just undoing the negative value that institutions have created. It’s not creating positive value. But I’m at least glad that we have the expertise to help clients navigate the bureaucratic BS more successfully and less stressfully.

Clarity on what you truly want is a magic unlock. It’s worth (constantly) working on.

As I mentioned at the top, I recently spent several days in San Francisco, where I used to live, pre-children.

I still love San Francisco. I love walking its streets. I love taking MUNI and BART. I love the food (I packed two loaves of Acme bread in my suitcase to take home). I love the staircases and public parks.

And during many of my visits since moving out almost 15 years ago, I used to yearn to live there again. During this recent visit, I found myself enjoying all that San Francisco has to offer, but without that yearning.

I was trying to figure out why my reaction to San Francisco was so purely appreciative this time, not tinged with yearning. It seems linked to another experience I’ve had recently: on various occasions walking around downtown Bellingham (where I live) with either my mom or a daughter, I’ve observed myself feeling deeply contented. So deep and thorough was this contentment that it felt heavy, tangible.

I think I can attribute these pleasures to two things:

  • Getting older. I turned 48 earlier this year. Being that 80-year-old woman rocking on the front porch who doesn’t give one sh*t what other people think? #goals I have a working hypothesis that women, much as we are born with all the eggs we’re ever going to have, we are also born with all the f*cks we’re ever going to have. And, as with eggs, we shed those f*cks steadily over our lifetime until arriving at a point when we, ta da! have no more f*cks to give.
  • Working explicitly, for years now, to clarify what I truly value, and taking explicit steps to use my time and money to support those things. You know, the answer to, “If I were to die tomorrow, what would I regret that I never did?” And it doesn’t hurt (from this perspective, at least) that I had to deal with a diagnosis of and treatment for Stage 0 breast cancer starting in August 2023; that has a way of focusing one’s attention. 😑

(Yes, I’m also affluent, healthy, lucky, etc. And there are plenty of people who are all those things…and also unhappy.)

In the past few years, I’ve really started prioritizing What Truly Matters to Me over the usual stuff that it’s so easy to fall into. That has meant I finally took my daughters (and my husband) to a long-yearned-for trip to London and Paris. I planned a lot for it. I saved for it over a year or two. I arranged work so that I could really be present on my travel and not constantly peeping back into work. And it. was. amazing. Everything I expected and more.

I better carved time out of my calendar to attend my kids’ track and cross-country meets and other school events. To start working with a personal trainer. I’ve spent more of my money getting together with my brother’s family because his daughter is the only cousin my kids have, and they get along so well.

I’ve started caring less (I still care…just less) about how my business stacks up against other people’s businesses. I decided that my focus was going to be making enough money, serving my clients well, and enjoying the work as best I could (i.e., paying to outsource or delegate the work I didn’t).

All that is great! But what are the flip-side implications of prioritizing all those things? It means that I simply can’t afford to live in San Francisco right now. I’d have to change how I run my business or my family life in major ways in order to do so. I think that used to make me sad. But I think it used to make me sad because I it felt like giving something up without acknowledging what I was prioritizing or gaining in return.

And while San Francisco is a great city, and I certainly wouldn’t sneeze at the idea of living there again, living in a great city like that isn’t in my top 5 right now. The work I’ve done to figure out what my top 5 is has been long and difficult and, ultimately, has made me a much more content person.

(Disclaimer: Contentedness of course subject to change at a moment’s notice, but I am optimistic I’m on the right path.)

Perspectives on the Financial Planning Profession. We’re Out There!

While I was in San Francisco, I met up with a few clients to just Talk Life (okay, and the occasional options-exercise strategy).

I met one client for lunch at Duboce Park Café on an unimpeachably beautiful day. I’ve been working with him for…Oh, I could look this up, but it’s probably two or three years. (Hey, there, guy! Yep, I’m talking about you.)

While I’m going to paraphrase tremendously here, he observed that he doesn’t hear any of his friends or colleagues talk about their financial advisors in a way that sounds anything like his relationship with me. He also recounted a conversation he had with a friend who asked him if he was still going to therapy, and he responded, Well, kind of. “What do you mean, kind of?” I meet with my financial planner every few months. “????”

As much as I preen at being viewed as The Only Emotionally Aware Financial Planner In the World, I will share with you what I shared with him: More of us are out there! I might be rare in a gigantic financial services industry, in my efforts to center the work on The Human instead of on The Money, in my efforts to continually dig into what my clients want their lives to look like and then to make financial decisions that support that life and set of values. But I’m definitely not alone.

In just the 8.5 years since I’ve been running my firm, I’ve noticed an absolute explosion of interest in, attention to, and training and content to support advisors becoming more human-centric, more emotionally attuned, more aware of the impact of behavior on financial outcomes, etc.

But I also recognize that I’m at a slight advantage over my client in knowing the financial planning landscape, being a financial planner and all. For Regular Schmoes out there, looking for a financial planner, I imagine that for every exposure they get to a planner like me, they get 1000 exposures to advisors from the likes of <insert name of gigantic financial institution here>. And while I have never worked at said gigantic financial institutions and don’t closely know advisors who do, I’m just gonna go ahead and bet that the vast majority of them—perhaps through no fault of their own—have a more money-centric approach to financial planning.

If you’ve never experienced the kind of financial planning that I (or my close colleagues) practice, it’s probably impossible to imagine if you’re accustomed to the service at Big Name financial companies.

Maybe I am, maybe I’m not the right financial planner for you, but I’m happy to connect you with other financial planners who operate in a human-centric way. Reach out and schedule a free consultation or send us an email.

Sign up for Flow’s twice-monthly blog email to stay on top of our blog posts and videos.

Disclaimer: This article is provided for educational, general information, and illustration purposes only. Nothing contained in the material constitutes tax advice, a recommendation for purchase or sale of any security, or investment advisory services. We encourage you to consult a financial planner, accountant, and/or legal counsel for advice specific to your situation. Reproduction of this material is prohibited without written permission from Flow Financial Planning, LLC, and all rights are reserved. Read the full Disclaimer.

More Strategies to Save You Taxes In Case the Tax Cuts and Jobs Act Expires in 2026

A shadowy Block Woman views a yellow ball labeled with red initials TCJA almost fully hidden below the horizon of a blue and green sea.

Big tax changes are a’ comin’. Maybe. In our last blog post, I discussed one big strategy to take advantage of the possible expiration of the Tax Cut and Jobs Act: the fabled Roth conversion.

The TCJA went into effect on January 1, 2018. All of the TCJA’s changes to tax law will expire at the end of 2025—and tax rates and other rules go back to the pre-2018 levels—unless Congress renews it.

In this blog post, let’s cover a few more strategies that might end up being really helpful to have done if the TCJA does indeed expire. But remember, because we don’t know whether the TCJA tax laws will expire or be renewed, you only want to make moves now if you’ll still be okay regardless of whether Congress renews it or lets it expire. Don’t go bettin’ the farm on Congress doing or not doing something.

And as with the previous blog post, it’s going to be Very Helpful to have a competent CPA on your team to help model the tax impact of any of these strategies.

Exercising Non-Qualified Stock Options (NSOs)

Remember how (and if you don’t, go back and reread our last blog post) I recommended that you consider converting pre-tax money in your IRAs or 401(k)s to a Roth account, because tax rates are low now compared to what they will be if the TCJA expires? And we want to incur taxable income when tax rates are lower?

Well, the exact same logic applies to the idea of exercising non-qualified stock options (NSOs).

When you exercise an NSO, you immediately owe income tax on the “spread” between the exercise price and the value of the stock.

Let’s say you exercise one NSO at a strike price of $1 with a share price of $10 (be that the price on the stock market for a public company, or the 409(a) value for a private company). That gives you $9 of taxable income.

Most people aren’t thinking about just one option. So, let’s think about 10,000 NSOs. In the exact price scenario above, you’d immediately have $90,000 of taxable income.

Behold the tax brackets and tax rates below, which is what they are now, and what they will be if the TCJA expires. Imagine that you’re single and your salary + bonus is $500k/year. If you exercise NSOs now, that generates an extra $90k of taxable income, all of that will be taxed at 35%. If you exercise post-TCJA expiration, then a little of that $90k will be taxed at 33%, a little at 35%, and most of it at 39.6%. Which, let’s review, is higher than 35%.

If you look long enough at the chart below, you can see that in some income scenarios, you’ll actually have a lower top tax rate post-TCJA than now. You’d need to run the numbers for your own specific situation to make sure.

Source: fpPathfinder®

Consider doing this: Exercise NSOs now, especially in private companies, if it would generate taxable income in a lower tax bracket than post-TCJA expiration. If you have NSOs in a public company, I’m usually of the opinion that you shouldn’t exercise NSOs until you’re ready to exercise and immediately sell, and that having the right amount of leverage is a good tool for determining when to do that. That’s probably still more important than gaming tax rates.

Exercising Incentive Stock Options (ISOs)

Surprisingly, most people I talk with who have ISOs seem to know about Alternative Minimum Tax. (Someone out there has been doing some good employee education!) The understanding sometimes stops right there: this tax exists, it’s related to ISOs, and, uh…tax bad?

For a short primer/reminder on AMT, read this blog post, the section entitled “Mistake #3: Forgetting about Alternative Minimum Tax on ISOs,” from our friends at McCarthy Tax.

What’s important in this blog post here is that the likelihood of having to pay AMT when you exercise ISOs will go up dramatically if the TCJA expires. You can usually exercise some ISOs without triggering AMT because there’s an “exemption” amount of AMT income before the tax kicks in.

Let’s say you exercise one ISO at a strike price of $1 with a share price of $10. That gives you $9 of AMT-eligible income. That income will likely not be subject to any tax because it’s below the exemption threshold.

At the other extreme, let’s say you exercise 100,000 such options, for $900,000 of AMT-eligible income (and then you hold the shares for at least a year). Yeah, you’re likely going to have to pay AMT.

You want to be pretty clear on where the tipping point is from “I don’t owe AMT” to “I owe AMT.”

That tipping point is determined in large part by what the AMT exemption amount is. The higher the exemption amount, the less likely you will have to pay AMT on your ISO exercises. You can see in the table below that right now, you can incur $133k of AMT-eligible income (as a couple; $85k as a single person) before triggering the tax. That threshold will drop meaningfully if TCJA expires: drop by roughly $29k for married couples filing jointly and roughly $19k for people filing taxes as Single.

Source: fpPathfinder®

Okay, what are you supposed to do with those numbers? Let’s continue with the example just above.

You can incur roughly $19k more AMT-eligible income now than you would be able to under the rules if TCJA weren’t in effect (all else held equal in your tax situation). So, with $9 of AMT-eligible income per option exercised, you could exercise roughly 2000 more ISOs now without triggering the Alternative Minimum Tax bill, than if you were exercising under tax rules without the TCJA in effect.

So, yes, you still have to pay the exercise price on that extra 2000 options (i.e., $2000, in this example), but you don’t have to pay anything more in taxes. Pretty sweet, eh?

Consider doing this: If you’re sitting on some exercisable ISOs (most likely that means they’re vested, but it could also mean you have early exercise/83(b) exercise available to you for unvested options), exercise ISOs now, up to the currently-higher AMT exemption limit.

Yes, you’re still putting your exercise price money at risk…but you’re not putting any money at risk paying taxes. You have up until the end of the year to do this. And then again in 2025.

[Note: Paying AMT isn’t the end of the world. If you pay it, you now have an AMT credit in your tax return, and if you make sure to carry it forward onto all subsequent tax returns, you have a chance of using that credit up in future years, thereby “getting back” any excess tax you paid in your AMT year. But, you know, it’s still nice to avoid paying it in the first place, as receiving the credit back isn’t guaranteed and also $1 now is better than $1 in 5 years. If you want to learn more about the AMT credit, see this blog post, the section “Mistake #4: Forgetting about the AMT Tax Credit”]

Increase your ability to exercise ISOs without AMT by increasing your ordinary income.

The higher your ordinary income, the higher your AMT income can be before triggering the tax. (This fact is independent of this TCJA discussion.) And increasing your ordinary income—by pulling future income into this year or 2025—might be a reasonable strategy to pursue in and of itself because your tax rates might be lower now than later.

What are some strategies for increasing your ordinary income?

In the tech world, it’s usually if you have non-qualified stock options to exercise. As discussed above, the spread between the strike price and share price is taxable ordinary income in the year you do the exercise. So, exercise more NSOs. Pay taxes on those (maybe at a lower tax rate than you’ll have in the future?) and then exercise even more ISOs without triggering AMT.

If you have any self-employment income or any other income whose timing you have control over, you could also consider accelerating income earlier rather than in later years.

Delay charitable contributions

The primary reason you should donate to charity is that you want to give money to a deserving cause or person. If you want to keep on keeping on in your annual charitable contributions, I APPLAUD YOU.

But if you’re already going to donate, you might as well make it as tax efficient as possible, eh?

There are two reasons that delaying charitable contributions might save you taxes:

#1 You save more when tax brackets are higher. If you are currently at a 37% tax bracket (the highest current tax rate) for every dollar you donate to charity (and itemize on your taxes), you save 37¢, which means it costs you 63¢ to donate that dollar. If you are at a 39.6% tax bracket (the highest rate in a post-TCJA world), you save 39.6¢ for every dollar you donate to charity, which means it costs you 0.604¢ to donate that dollar to charity.

Purely from that perspective, it makes sense to donate money in years when you’re in a higher tax bracket.

If you think tax brackets could rise in 2026, maybe it’d behoove you to delay charitable giving until 2026, when you could “bunch” charitable contributions from 2024, 2025, and 2026 into 2026. That way you’d get the benefit of bunching (a strategy that can be useful no matter what the tax-rate regime) and you’d be saving taxes at higher tax rates.

I wrote a series of blog posts about creating my family’s charitable giving plan, and it covers tactics we employed to make it more tax efficient, like donating “appreciated securities” instead of cash and the just-mentioned “bunching” of multiple years’ worth of donations into one year.

#2 You’re more likely to itemize—and actually get tax benefits—if TCJA expires. Also changing if TCJA expires is the standard exemption: it’d go down a lot:

Source: fpPathfinder®

You also will be allowed to itemize much more of what are often people’s two biggest expenses: mortgage interest and state and local taxes.

Right now, you can itemize interest on mortgages only up to $750k. That’d change to $1M. (And in places like the Bay Area and NYC, it’s reeaaaaallll easy to get a mortgage that big.)

Secondly, right now you can deduct only $10k of your state and local taxes (known as SALT). Again, if you live in California or NYC, your state and local taxes are likely way more than that.

Thirdly, and probably less impactfully, is that you could once again deduct the fees associated with using an investment advisor. (Thought I’d throw that in there for, you know, self-promotion’s sake.)

Source: fpPathfinder®

So, now you have a lower standard deduction and you’re being allowed to itemize more things, meaning it’s easier to get to the point where it’s worthwhile to itemize deductions because they exceed the standard deduction.

Consider doing this: Delay your charitable contributions to 2026. Between potentially higher income tax rates at that point, and the increased ease of itemizing deductions over taking the standard deduction, this could save you meaningfully in taxes.

Please return to my first comment in this section: the primary reason to donate money is to help people or causes, not to save in taxes.

If you're high net worth, get more assets out of your estate.

There’s too much to think about here, for this one blog post. I would absolutely encourage you to talk about this with your estate planning attorney (and/or your financial planner) .

What’s going on? When you die, any money in your estate above a certain threshold will be subject to a federal estate tax of up to 40%. (Look here for details. Some states also have estate/death/inheritance taxes, but we’re not discussing those.) Right now, that exemption is $13,610,000 per person. If TCJA expires, it’ll drop back down to what is currently estimated at $6,810,000.

Source: fpPathfinder®

Which means that if you have $10M now and die, your estate won’t have to pay any estate taxes and your heirs get all your money. If you were to die in a TCJA-expired world, $3,900,000 of your estate would be subject to estate tax, and your heirs would lose a lot of money to estate taxes.

Maybe you don’t have $10M now. But, you do have $5M, and if you live another 20+ years, and that money is invested and grows, you will have a bunch of money when you die. And then your heirs could still miss out on a lot of money because of estate taxes.

In either case, the overarching strategy being widely discussed now is to move money out of your estate now, when you have that big ol’ $13,610,000 lifetime exemption available to you. You can move your money out of your estate in a variety of ways, from plain vanilla (like funding your child’s 529 college savings account) to more complicated (like family limited partnerships and Nevada Asset Protection Trusts…no, I don’t actually know how these work, I’ve simply spoken with estate planning attorneys who do).

There is so much more to this discussion. Way more information is necessary from attorneys far more knowledgeable than I. This mention is only an amuse-bouche.

The benefits of moving money out of your estate now are the more obvious: Possibly saving your heirs a lot of estate tax.

In my opinion, there are a couple of major downsides to moving money out of your estate now:

  • Complexity: Your financial situation is almost certainly going to get more complex, with more accounts or legal structures to keep track of, and possibly changes to how you access your money/get income. Simplicity is worth fighting for.

  • Reduced access/flexibility: Your access to your money is almost certainly going to be more constrained, and possibly just outright reduced. Moving money out of your estate more or less means that it’s no longer yours to control and use as you want.

    I believe that the younger you are, the more important this is to consider. With so many years of life ahead of you, life is nothing but Uncertainty. Flexibility is a powerful tool in such circumstances.

    As one of my favorite estate planning attorneys observed, you might want to retain all your money unencumbered because, who knows! You might want to emigrate to a different country, buy your own baseball team, start a business, or start a foundation. And who knows what kind of adult your three year old is going to turn into in another two decades.

If you’re 80 and have 10, maybe 20 years left, this decision is one thing. But if you’re 40 and have two young kids and have half a century of life unfolding in front of you? Putting any of your money out of your control is, in my opinion, a risky gambit.

To boot, who knows what estate rules will be when you eventually die (hopefully, decades from now, by which time Congress will likely have changed the rules another 10 times)?

Consider doing this: Talk with an estate planning attorney who is familiar with the strategies necessary to move money out of your estate. But do this well before the end of 2025, because they are going to be slammed by then! It’d be like trying to hire a CPA in March to do your taxes by April 15. By which I mean: Good luck with that, yo.

Blog posts like this actually make me a bit anxious. There’s so much finicky stuff to keep on top of! I can only imagine how thinking about this must affect people who aren’t financial planners.

Just try to keep in mind that these strategies are not the essence of personal finance. The essence of personal finance is: spend less, save more, and don’t do anything stupid (according to Dick Wagner). If you’re not doing those things yet, focus your effort there first!

Would you like to work with a financial planner who can help proactively identify opportunities like this and then figure out whether they’re useful for you and your finances? Reach out and schedule a free consultation or send us an email.

Sign up for Flow’s twice-monthly blog email to stay on top of our blog posts and videos.

Disclaimer: This article is provided for educational, general information, and illustration purposes only. Nothing contained in the material constitutes tax advice, a recommendation for purchase or sale of any security, or investment advisory services. We encourage you to consult a financial planner, accountant, and/or legal counsel for advice specific to your situation. Reproduction of this material is prohibited without written permission from Flow Financial Planning, LLC, and all rights are reserved. Read the full Disclaimer.

Should you do a Roth conversion before the (possible) expiration of TCJA in 2026?

A shadowy Block Woman views a yellow ball labeled with red initials TCJA partially below the horizon of a blue and green sea.

As you might know, there’s a huge, all-encompassing change to tax law potentially coming up at the end of 2025. If it happens, you will almost certainly be big-time impacted.

What is that all-encompassing change to tax law? It’s the expiration of the Tax Cut and Jobs Act, which went into effect on January 1, 2018. All of the changes the TCJA ushered in will expire at the end of 2025—and tax rates and other rules therefore go back to the pre-2018 levels—unless Congress renews it.

It’s anybody’s guess whether Congress will renew it.

There are many provisions in the TCJA that really benefit our clients. If you, like our clients, are in tech, make good money and/or have good wealth, and have various forms of equity compensation, you probably benefit, too.

So, it behooves us to look at what tax rules are in effect now that potentially will disappear come 2026, and ask ourselves:

Should we take advantage of TCJA tax rules while they still definitely exist (because they might not exist come 2026)?

Consider these strategies this year and next.

Given the “maybe?” nature of all of this, you don’t want to do anything that you’ll regret if the tax laws stay the same. So, you’re looking for strategies that will serve you well—or at least not hurt you—regardless of what happens tax-wise.

This is, may I remind you, the nature of almost all of personal financial planning: You’re making decisions based on what you think or hope will happen in the future, not on what you know will happen in the future.

How do you still make good decisions in an environment of such irreducible uncertainty? For each choice available to you, you need to think about all the possible outcomes of making that choice. If any of those outcomes is simply unacceptable, then that choice isn’t right for you.

If some outcomes are better or worse than others, but none of them would be catastrophically bad for you (financially or emotionally), then it could be a reasonable choice to make.

For example, let’s say you work at a pre-IPO company. You have stock options. You could exercise them now, paying not only the exercise cost but also the associated tax bill. You can’t know what will happen to the company, and more specifically, the stock, in the future. Let’s say the stock does poorly and you lose all that money.

  • If that means you’d lose your emergency fund and throw your retirement plans off track, then that’s not a reasonable choice.
  • If that instead means you can’t take that One Vacation, but you’re more or less okay with missing it, then okay! Go forth and take that risk.

Below I discuss one strategy to consider before the TCJA expires (maybe): Roth conversions (and the corollary: contributing Roth instead of pre-tax). Later this month, I’ll publish another blog with the other strategies I think are worth considering:

  • Exercising ISOs
  • Delaying charitable contributions
  • All sorts of potentially very complicated stuff to reduce the size of your estate (for those of you who already have millions of dollars)

I’m covering only those strategies that I think are most likely to affect our clients (and therefore you, if you’re like our clients). The changes made by the TCJA are vast and beyond the scope of this blog post.

If you want to know more about the whole TCJA “thing,” you can find articles that are broader in scope from the likes of Schwab or Forbes or any number of financial advisory firms focused on other clientele.

Why talk about this now?

The changes may or may not happen, and making giant decisions based on a possibility is often a bad idea.

But we’re talking about it now for a few reasons:

  • There are some potentially powerful strategies you can use for 2024 and 2025 that will lose their power come 2026, if TCJA expires.
  • If you need to involve an estate planning attorney in any work, they’re gonna be slammed come the latter half of 2025. Best to reach out to them ASAP.
  • Even if it were entirely rational to wait for a while to discuss any of this stuff, you’re going to start seeing some “sky is falling” headlines, if you haven’t already. So, let’s discuss this in a useful manner before the headlines hijack your brain.

Roth conversions: Convert pre-tax IRA or 401(k) dollars to Roth

Why do we care about pre-tax and Roth?

Some background and edumuhcation about Pre-tax vs. Roth

Let me ask you a question: Would you rather save pre-tax when your tax rates are high or low?

The answer is High. If your tax rate is 39%, every dollar saved pre-tax saves you 39¢ in taxes. If your tax rate is 25%, every dollar saved pretax saves you 25¢. Saving 39¢ is better.

Now, would you rather save after-tax (i.e., to a Roth account) when tax rates are high or low?

The answer is Low. At a 39% tax rate, you pay 39¢ in taxes for every dollar you save to a Roth account. At a 25% tax rate, you pay 25¢ for every dollar you save to a Roth account. Paying 25¢ is better.

That’s a useful, but simplistic, way of thinking about the pre-tax vs. Roth/after-tax question. For a bit more nuance:

When you take money out of pre-tax accounts (typically IRAs or 401(k)s) in retirement:

  • You will need to pay income tax on all of that money.
  • That income can also increase other costs, like Medicare Parts B and D premium and the taxability of your Social Security retirement income.
  • All money in a pre-tax IRA or 401(k) is subject to Required Minimum Distributions, meaning that you must take money out of those accounts starting at what is now age 73.

Sounds kinda crappy. Why would we put money into a pre-tax account? Why, to save money on taxes now, of course.

By contrast, Roth accounts are tax-free, and any money in those accounts can stay in there for your whole life, you never have to take the money out, and if you do, it’s not subject to taxes and won’t raise your taxable income in a way that will impact Medicare premiums, etc. But you don’t get any tax breaks now for any contributions or conversions into Roth accounts.

[Note: The “Roth vs Pre-tax” discussion is a multi-layered one. Some considerations are technical (comparing current tax rates with expected future tax rates). Some are emotional (I, for example, would rather just bulk up tax-free assets while I’m young and have strong earning power). This TCJA-inspired consideration has to fit into the larger Roth vs. Pre-Tax discussion, which is, alas! outside the scope of this blog post.]

Why now is such a good time to consider Roth conversions

I wrote a whole blog post about Roth conversions a little while ago. (If you think you want to do a Roth conversion, I highly recommend you read the whole thing. Oh, and work with a CPA to model the tax impact.)

In that post, I pronounced that one good opportunity for doing Roth conversions is when “You bet the federal government will raise tax rates.” Well….?! That’s precisely what we’re talking about here!

If TCJA expires, here’s how tax rates and tax brackets would change. Observe that not only do tax rates go up, but higher tax rates apply to lower bands of income, meaning that your tax bill could go up double-whammy style.

Source: fpPathfinder®

We already consider Roth conversions for clients who are having an unusually low-income year, clients who are taking a sabbatical, going back to school, got laid off and can’t find a job, etc.

Because of this TCJA thing, even if this is a totally “normal” income year, you should still look at doing Roth conversions. These might end up being anomalously low tax rates anyways, simply because of federal tax policy.

Keep in mind that doing a Roth conversion means you are volunteering to pay taxes before you have to. You could just wait for another several decades to pay taxes on this money. But you’re making a bet that by paying taxes now, you’ll pay less (over your lifetime) than if you pay taxes later. (So much delayed gratification energy going on here, it hurts.)

It’s always possible you could convert the pre-tax money, and the tax rates don’t go up. Lord knows there have been bountiful predictions for decades now that tax rates will (“have to!”) go up…predictions that have yet to come true.

Consider doing this: Ask your CPA to model for you how much you can convert from pre-tax to Roth (in your IRA or 401(k)) and still stay within the same tax bracket, or even one tax bracket up, along with the tax bill you’d incur in both cases. If you want to convert, remember you have to do so by year’s end. You can even convert some this year and some again next year.

Remember, you want to have cash or taxable investments to pay the extra taxes. You do not want to withhold any money from the IRA in order to pay the taxes.

Contribute Roth instead of pre-tax

Many of our clients have $100ks or over $1M in pre-tax accounts (IRAs or 401(k)s). That is a lot of money to consider converting. (In reality, it probably makes sense to convert only some of it.)

By contrast, annual contribution limits to all these retirement accounts are way way lower: $23,000 for 401(k)s and $7k for IRAs (plus some catchup for people 50 years old and up). So, “pre-tax vs. Roth contribution” can be a much smaller-scale decision.

It’s still worthwhile considering, however! And maybe, behaviorally speaking, it’s a lot easier to contribute Roth (and not reduce your tax bill) than it is to convert to Roth (and intentionally increase your tax bill, possibly by a lot). Progress, not perfection, people!

Many of you likely have access to, and perhaps are even saving to, after-tax contributions to your 401(k) (aka, mega backdoor Roth). In that case, you’re already getting lots of after-tax/tax-free money into your retirement portfolio. Maybe that takes the pressure off shifting even more money into that tax-free status.

Consider doing this: Saving to your 401(k) Roth instead of pre-tax, for the rest of this year and in 2025. You could switch back to saving pre-tax if TCJA expires and tax rates jump up.

It’s hard to figure out how all this affects you!

I don’t know if you’ve noticed this, but our federal tax code is complicated. Like, really, really complicated. And getting more so every year. (Be sure to give your friendly local CPA a sympathetic glance, and maybe a cookie, next time you see them.)

The tax code is so intricate and interrelated that you can’t ever glibly proclaim that the change of <this one thing> will affect your taxes <in this specific way>. You need tax software because you need to effectively process your entire tax return in order to get a reliable answer about any single thing. It’s an unfortunate reality.

For example, if you live in California and have a mortgage and earn a lot of money, the higher tax rates will hurt you, but your ability to deduct more of your mortgage and more of your state income taxes (as illustrated below) will help you.

Source: fpPathfinder®

To make good decisions confidently, you need to work with a tax professional who has software that can model your entire tax situation under TCJA tax rules vs. your tax situation if TCJA expires.

Alright, friends and strangers. See you in the next blog, for more discussions of strategies you should start considering before the end of this tax year. Tootles.

Would you like to work with a thinking partner who can help you to discover and define your goals, and use that to help make your best financial decisions? Reach out and schedule a free consultation or send us an email.

Sign up for Flow’s twice-monthly blog email to stay on top of our blog posts and videos.

Disclaimer: This article is provided for educational, general information, and illustration purposes only. Nothing contained in the material constitutes tax advice, a recommendation for purchase or sale of any security, or investment advisory services. We encourage you to consult a financial planner, accountant, and/or legal counsel for advice specific to your situation. Reproduction of this material is prohibited without written permission from Flow Financial Planning, LLC, and all rights are reserved. Read the full Disclaimer.